Chapter 7 Means Test: Deterministic vs. AI-Estimated (August 2026)
Your means test result is only as reliable as the method behind it. Run the same inputs through an AI-estimation tool twice and you may get two different numbers. Run them through deterministic statutory logic and you get the same auditable answer every time. With courts increasingly reviewing AI use in filings, understanding which kind of calculation you're relying on could save you from a very uncomfortable trustee objection.
TLDR:
- The means test gates Chapter 7 eligibility and sets Chapter 13 plan length using a 6-month income lookback against state medians.
- Above-median filers still pass Chapter 7 roughly 12% of the time once IRS standard deductions apply to disposable income.
- AI-estimated means test calculations can vary on re-runs and cannot be traced to a statutory rule, creating perjury exposure on signed petitions.
- Bankruptcy judges in Illinois, South Carolina, and Alabama have sanctioned attorneys for AI-generated filing inaccuracies, per Bloomberg Law.
- Glade AI runs means test calculations through fixed, rule-based logic with auto-updating U.S. Trustee median tables, keeping every output auditable and defensible.
What the Bankruptcy Means Test Actually Is
The means test is the income screen deciding whether a filer belongs in Chapter 7 or gets routed into Chapter 13. Congress built it into the Bankruptcy Abuse Prevention and Consumer Protection Act of 2005, codified at 11 U.S.C. § 707(b), to keep higher-income debtors from wiping out debt they could reasonably repay. For a broader overview, see the AI for bankruptcy law 2026 guide.
Most individual consumer debtors complete a version of Official Bankruptcy Form 122. The math compares a debtor's income against the state median and, for above-median filers, weighs disposable income against allowed expenses.
Treat it as an eligibility gate, not a penalty. It sorts filers by what they can afford to pay, nothing more.
How the Chapter 7 Means Test Works
Start with Current Monthly Income. Add up everything the debtor earned across the six full calendar months before filing, average it, then multiply by 12 to annualize.
Part 1 is the median comparison. If annualized CMI lands at or below the state median for the debtor's household size, the debtor passes automatically. No further math runs.
Above the median, Part 2 kicks in. Subtract allowed deductions:
- IRS National and Local Standards for living expenses
- actual secured debt payments
- taxes, health insurance, childcare, and other permitted costs
What remains is monthly disposable income. Multiply it by 60 for the five-year figure the statute measures against its thresholds. Roughly 12% of Chapter 7 filers sit above median and still clear the test once deductions apply (U.S. Trustee Program data).
What Income Counts and What Does Not
The test runs on gross employment income, not take-home pay. Wages count before taxes, retirement, and withholdings come out.
The lookback covers the six full calendar months before filing. The month of filing drops out, since it is rarely complete. That mechanic matters more than it looks.
What lands in Current Monthly Income:
- gross wages, salary, bonuses, and overtime
- net self-employment income
- rental income
- regular contributions from household members
Social Security benefits sit outside CMI. The statute excludes them.
Timing becomes strategy. A raise inside the window inflates the average; a recent job loss drags it down as older high-income months roll off. Pick the filing date deliberately. Firms looking into law automation benefits and use cases often start here.
Some debtors skip the test: those with primarily business debts, certain disabled veterans, and certain active-duty service members.
The 2026 Median Income Updates and How They Affect Eligibility
The U.S. Trustee Program refreshed its median income figures on April 1, 2026, applying new Census Bureau data to every case filed on or after that date. A second update on July 15, 2026 adjusted the IRS Administrative Expense Multipliers and Local Standards that feed above-median deductions.
These figures move roughly twice a year, and the number that governs is the one in effect on your filing date, not the one you found months earlier.
That timing carries weight for anyone near the line. A New York filer who sat just above median in late 2025 may clear the updated 2026 threshold with no change in actual income. Confirm current figures on the U.S. Trustee Program means testing page before filing.
How the Chapter 13 Means Test Differs From Chapter 7
In Chapter 13, the means test answers a different question. With no income ceiling, it never decides eligibility. It sets plan length and the minimum you pay unsecured creditors.
Form 122C-1 calculates CMI and fixes the applicable commitment period:
- below-median debtors: typically a 3-year plan
- above-median debtors: a required 5-year, 60-month plan
For above-median filers, Form 122C-2 runs the same IRS standard expense deductions the Chapter 7 test uses. What remains is projected disposable income, the floor for unsecured creditor payments.
Below-median debtors skip Form 122C-2, calculating disposable income from actual monthly expenses on Schedules I and J instead of IRS standards. For context on how AI in bankruptcy law is reshaping these workflows, see our full breakdown.
What Goes Into the Chapter 13 Payment Plan Calculation
The monthly payment satisfies several requirements at once, and the highest floor wins:
- priority debts like back taxes and domestic support paid in full
- secured creditors paid at least the value of their collateral
- unsecured creditors receiving no less than a hypothetical Chapter 7 liquidation would yield, the best-interests test
- the trustee's administrative fee, typically 6 to 10% of plan payments; AI-powered paystubs and bank statements can accelerate populating these figures
For above-median debtors, Form 122C-2 disposable income sets a floor on the unsecured portion.
Picture a debtor with $600 left after Schedule J. A $9,000 car and $2,000 in back taxes come first over the 60-month plan, and with the trustee fee they absorb most of that $600. Below-median filers can leave unsecured creditors close to nothing. An above-median debtor with $1,400 in Form 122C-2 disposable income faces that figure as a hard floor.
Deterministic vs. AI-Estimated Means Test Calculations
A deterministic means test runs fixed statutory formulas against the debtor's income, household size, state median, and IRS standard figures. The result is reproducible, auditable, and traceable to the exact rule that fired. Re-run it a hundred times and you get the same number.
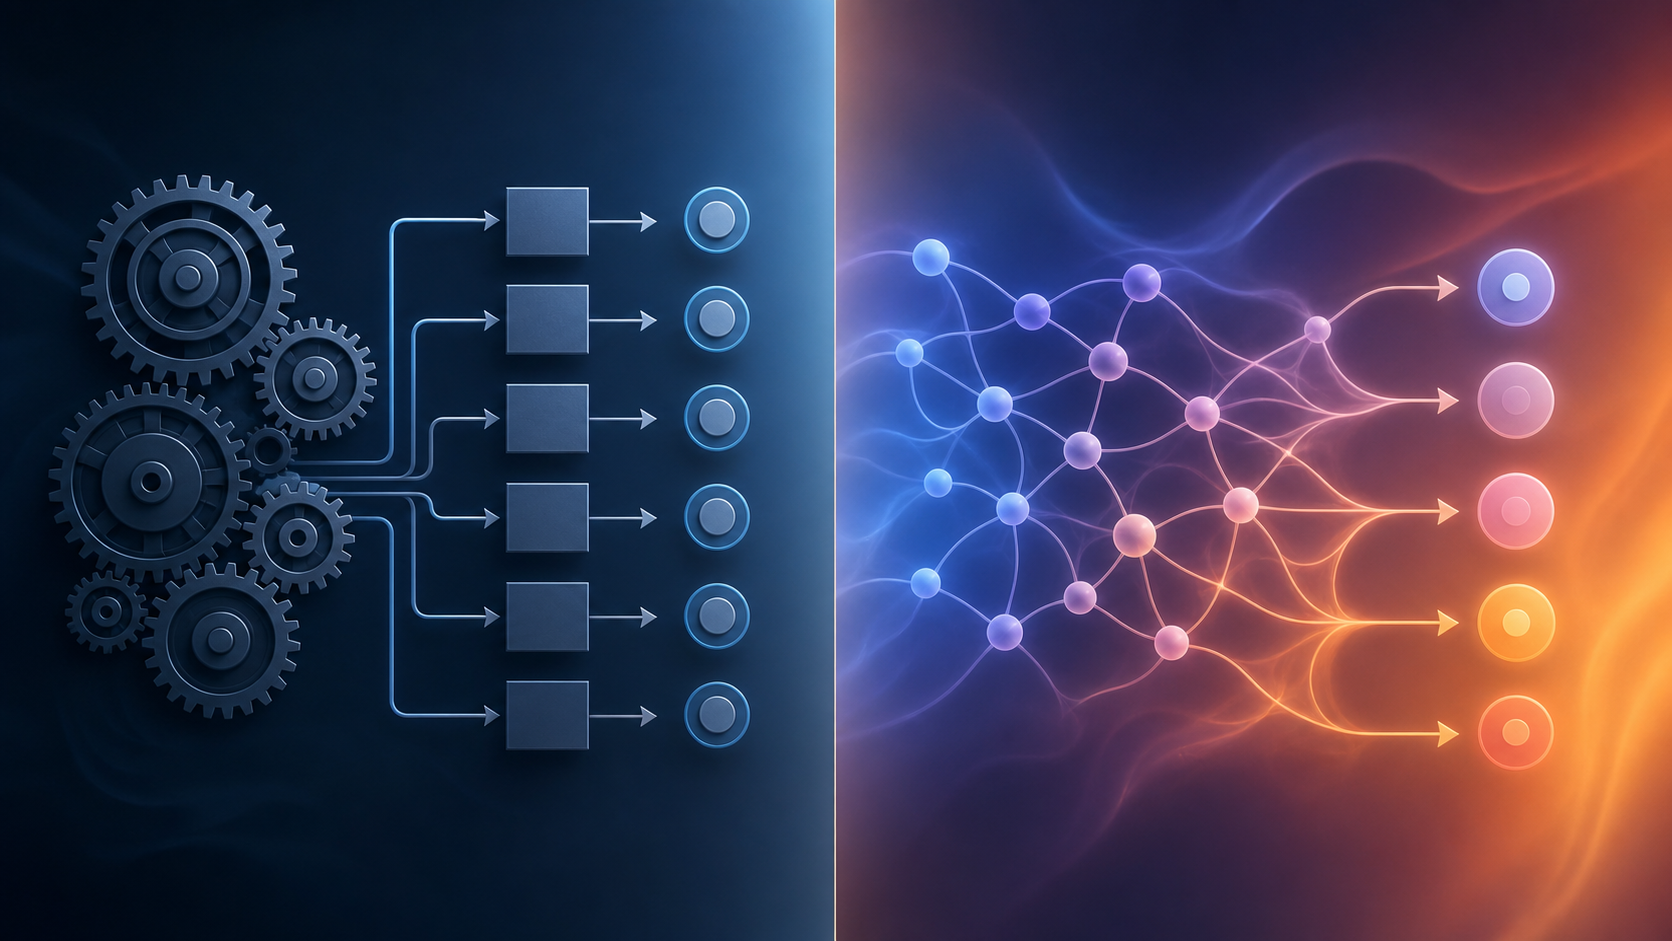
An AI-estimated calculation pattern-matches to approximate an output. It can vary on re-runs, cannot be traced to a specific statutory rule, and may miss the correct figure when Census or IRS tables change mid-year.
The table below reflects Glade's own architectural approach compared to general-purpose AI tools used for statutory calculations, based on publicly available information as of July 2026. Individual tools vary; consult each vendor's documentation for current capabilities.
Deterministic Calculation | AI-Estimated Calculation | |
|---|---|---|
Output consistency | Same result every run | Can vary on re-runs |
Traceability | Every number tied to a specific statutory rule | Cannot be traced to a statutory provision |
Median table updates | Syncs automatically when U.S. Trustee figures publish | May miss mid-year Census or IRS table changes |
Perjury exposure | Low: auditable, defensible output | Higher: wrong figure can trigger presumption of abuse |
Trustee objection risk | Low: result reproducible and rule-traceable | Higher: pattern-matched approximation may not hold up |
That gap matters because the petition is signed under penalty of perjury. A wrong figure can trigger a presumption of abuse, a trustee objection, or dismissal, which is why practices focused on reducing manual entry for bankruptcy firms treat deterministic math as non-negotiable.
Courts have noticed. Bankruptcy judges in Illinois and South Carolina sanctioned attorneys for filings containing AI-generated inaccuracies, and an Alabama judge ordered an attorney to show cause over fabricated citations, according to Bloomberg Law. In July 2026, the Eleventh Circuit reprimanded a Florida attorney for briefs with fabricated AI-generated citations, referring him to its disciplinary committee.
What Online Means Test Calculators Can and Cannot Do
A well-built online calculator gives a fast read: it runs your income against current median tables and IRS standard deductions to flag whether you land below median, above median but likely still eligible, or probably ineligible for Chapter 7.
The limits are real:
- most use state-level housing and utility averages; the official form needs county-level data
- they cannot handle seasonal income, a one-time bonus, or mid-year job loss
- they cannot flag prior transfers, recent creditor payments, or non-exempt asset exposure
Treat it as an educational screener, not a stand-in for the official forms run against verified, current figures. Firms that need more precision often turn to a custom-built AI solution for their bankruptcy firm.
Means Test Exemptions and Special Circumstances
Failing the basic math is not always the end of the analysis. Some debtors skip the test, and some who fail Part 2 still reach Chapter 7.
Three statutory exemptions remove the presumption of abuse outright:
- debtors whose obligations are primarily business debts, not consumer debts
- disabled veterans whose disability was incurred during active duty or homeland defense activity
- active-duty service members and reservists called up for 90 or more days within the preceding 540 days
Above-median debtors who fail both parts have one more path. Under 11 U.S.C. § 707(b)(2)(B), documented special circumstances can support additional expense adjustments where no reasonable alternative exists, serious ongoing medical costs being the common example. The claim requires written documentation and itemized figures, and the court weighs it case by case.
How Glade AI Handles Means Test Calculations for High-Volume Firms
Here is where the deterministic-vs-AI-estimated distinction stops being theory and becomes architecture. Glade's means test engine runs fixed, rule-based math against statutory thresholds, never through an AI inference layer, so every output is reproducible, auditable, and traceable to the exact rule that fired. For an attorney signing under penalty of perjury, that is the difference between a calculation you can defend and one you cannot. See how a high-volume bankruptcy firm overhauled its workflow using this same approach.
The pieces around it remove stale-data and manual-keying risks:
- Median income tables from the U.S. Trustee Program, including the April 1, 2026 refresh, load automatically the moment they publish.
- The Income Organizer extracts paystub income on upload with no keying and updates the means test in real time.
For Chapter 13, the Chapter 13 Plan Calculator surfaces median status, required unsecured payout with means-test and liquidation binding-row logic, and payment capacity the moment income data populates, giving a feasibility read before petition assembly starts. AI handles parsing through the AI Schedules Builder and Case Intelligence; deterministic logic owns every statutory number. Learn how Glade AI bankruptcy automation puts this into practice for high-volume firms.
Final Thoughts on Passing the Bankruptcy Means Test
The six-month lookback, the filing date, and the current median tables are the three variables that actually move the needle on eligibility. Knowing which income counts, which exemptions apply, and when to file gives you real room to work with before the petition goes out. Book a demo to see how Glade runs this math with deterministic logic tied to automatically updated U.S. Trustee figures.
FAQs
Do I qualify for Chapter 7 if my income is above the state median?
Passing the median income threshold on the Chapter 7 means test is not the only path to eligibility. Above-median filers move to Part 2, where IRS National and Local Standards, actual secured debt payments, taxes, and other permitted deductions are subtracted from Current Monthly Income. What remains after those deductions, multiplied by 60, is measured against statutory thresholds. A high gross income figure does not automatically close the Chapter 7 door.
What is the difference between a deterministic means test calculator and an AI-estimated one for bankruptcy filings?
A deterministic calculator produces the same auditable result every run; an AI-estimated one pattern-matches and can vary, creating perjury exposure when the petition is signed under penalty of perjury and a wrong figure can trigger a presumption of abuse or trustee objection. Bankruptcy judges in Illinois, South Carolina, and Alabama have sanctioned attorneys for filings containing AI-generated inaccuracies, and the Eleventh Circuit rebuked an attorney in July 2026 for briefs with fabricated citations.
How does the Chapter 13 means test calculator differ from the Chapter 7 means test worksheet?
The Chapter 7 means test worksheet (Form 122A-1) functions as an eligibility gate: if annualized Current Monthly Income exceeds the state median and disposable income clears the Part 2 threshold, the debtor cannot file Chapter 7. The Chapter 13 means test on Form 122C-1 and 122C-2 answers a different question entirely. There is no income ceiling for Chapter 13 eligibility; instead, the calculation sets plan length (36 months for below-median debtors, 60 months for above-median) and floors the minimum payment to unsecured creditors for above-median filers using the same IRS standard deductions the Chapter 7 form uses.
Free means test calculator vs. Glade AI for a high-volume Chapter 7 or Chapter 13 practice: which should my firm use?
A free online means test calculator works as an educational screener: it flags whether a debtor lands below median, likely above-median-but-eligible, or probably ineligible for Chapter 7. The limits matter at filing volume: most use state-level housing averages where the official form requires county-level data, and none can handle seasonal income, a mid-year job loss, or a bi-weekly pay schedule where 13 paychecks fall inside the six-month CMI window. For firms processing 50-plus cases a month, Glade's deterministic means test engine runs fixed statutory math against current U.S. Trustee Program median income tables, including the April 1, 2026 refresh, updates automatically when new figures publish, and fires the moment paystubs hit the Income Organizer, so eligibility is surfaced before petition assembly starts instead of caught during attorney review.
How do I calculate disposable income for a Chapter 13 plan, and what sets the monthly payment floor?
For above-median debtors, Form 122C-2 subtracts IRS standard expense deductions from Current Monthly Income; what remains is projected disposable income and sets the floor for unsecured creditor payments across the 60-month plan. Below-median debtors skip Form 122C-2 and calculate disposable income from actual monthly figures on Schedules I and J instead. The plan payment itself must satisfy whichever requirement produces the highest floor: priority debts paid in full, secured creditors paid at least collateral value, unsecured creditors receiving no less than a Chapter 7 liquidation would yield under the best-interests test, and the trustee's administrative fee (typically 6 to 10% of plan payments) on top.