AI Paystub Parsing for Bankruptcy Petition Income Sep 2026
The CMI calculation is only as good as the paystub data feeding it. When a paralegal reads gross wages, taxes, and withholdings off each stub and keys them by hand, every transcription error carries forward into Form 122, Schedule I, and the means-test result. Here's how AI extraction changes that step.
TLDR:
- AI paystub parsing pulls gross pay, taxes, and deductions into calculation-ready numbers for Form 122, Schedule I, and the means test
- Current Monthly Income runs on a six-month lookback, so miskeyed paystubs can file an ineligible case or misprice a five-year plan
- Watch the bi-weekly 13th check: sum-and-divide averaging catches it; fixed multipliers over-weight income and inflate CMI
- Handwritten stubs, gig income, and cash pay still need manual keying and attorney review before any figure hits PACER
- Glade AI converts uploaded paystubs to Schedule I income with deterministic means-test math, collapsing 8+ hour petition prep into under 2 hours
How AI Paystub Parsing Fits Into Bankruptcy Petition Prep
Those paystubs feed three places at once: the Current Monthly Income calculation on Form 122, Schedule I, and the means test that routes a case into Chapter 7 or Chapter 13. Get the income figure wrong and every downstream number moves with it.
AI paystub parsing is automated line-item extraction from client-uploaded paystubs, one application of AI in bankruptcy law that's reshaping petition prep. Instead of a paralegal reading gross wages, taxes, retirement, and withholdings off each stub and keying them into a spreadsheet, an AI agent pulls those fields and hands back structured, calculation-ready numbers. For firms preparing Chapter 7 and Chapter 13 petitions at volume, that extraction step is where petition prep either flows or stalls.
Why Paystub Income Is the Foundation of the Means Test
Current Monthly Income drives the means test under § 707(b), built from a six-month lookback. Total every dollar the debtor received in the six full calendar months before filing, divide by six, and you have the monthly figure the test runs on. A raise or a lost job inside that window moves the number.
That average lands on Form 122A-1 for Chapter 7, carries into Form 122A-2 when the debtor is above median, and populates Form 122C-1 in Chapter 13. Against the state median, CMI decides Chapter 7 eligibility and sets the disposable-income floor for a Chapter 13 plan payment, a process covered in depth in the AI for bankruptcy law guide. Miskey the paystubs and you either file an ineligible case or misprice a five-year plan.
Why Hand-Keying Paystub Income Creates Petition Errors
It's 6 p.m., the petition's due tomorrow, and six months of paystubs are still a stack of PDFs nobody has keyed in. A paralegal reads each stub, pulls gross pay, taxes, retirement contributions, and withholdings, then types every line into a spreadsheet and averages by hand, exactly the kind of manual data entry in bankruptcy prep.
The friction shows up fast. Pay periods vary, so weekly, bi-weekly, and semi-monthly stubs each need different math. Paychecks go missing from the window, forcing follow-up requests that stall the case. And every transcription error, a transposed digit or a skipped deduction, carries forward into CMI, Form 122, Schedule I, and the means-test result. One mistyped number at the top means checking the whole petition to find where it went wrong.
How AI Paystub Parsing Extracts and Structures Income Data
A parser reads a paystub the way a paralegal would, then structures the output. It pulls gross pay, net pay, pay date, and pay period, then breaks out each deduction line: federal and state taxes, Social Security, retirement contributions, health insurance, and other withholdings. Year-to-date columns come through alongside current-period figures, since YTD totals drive single-paystub income math.
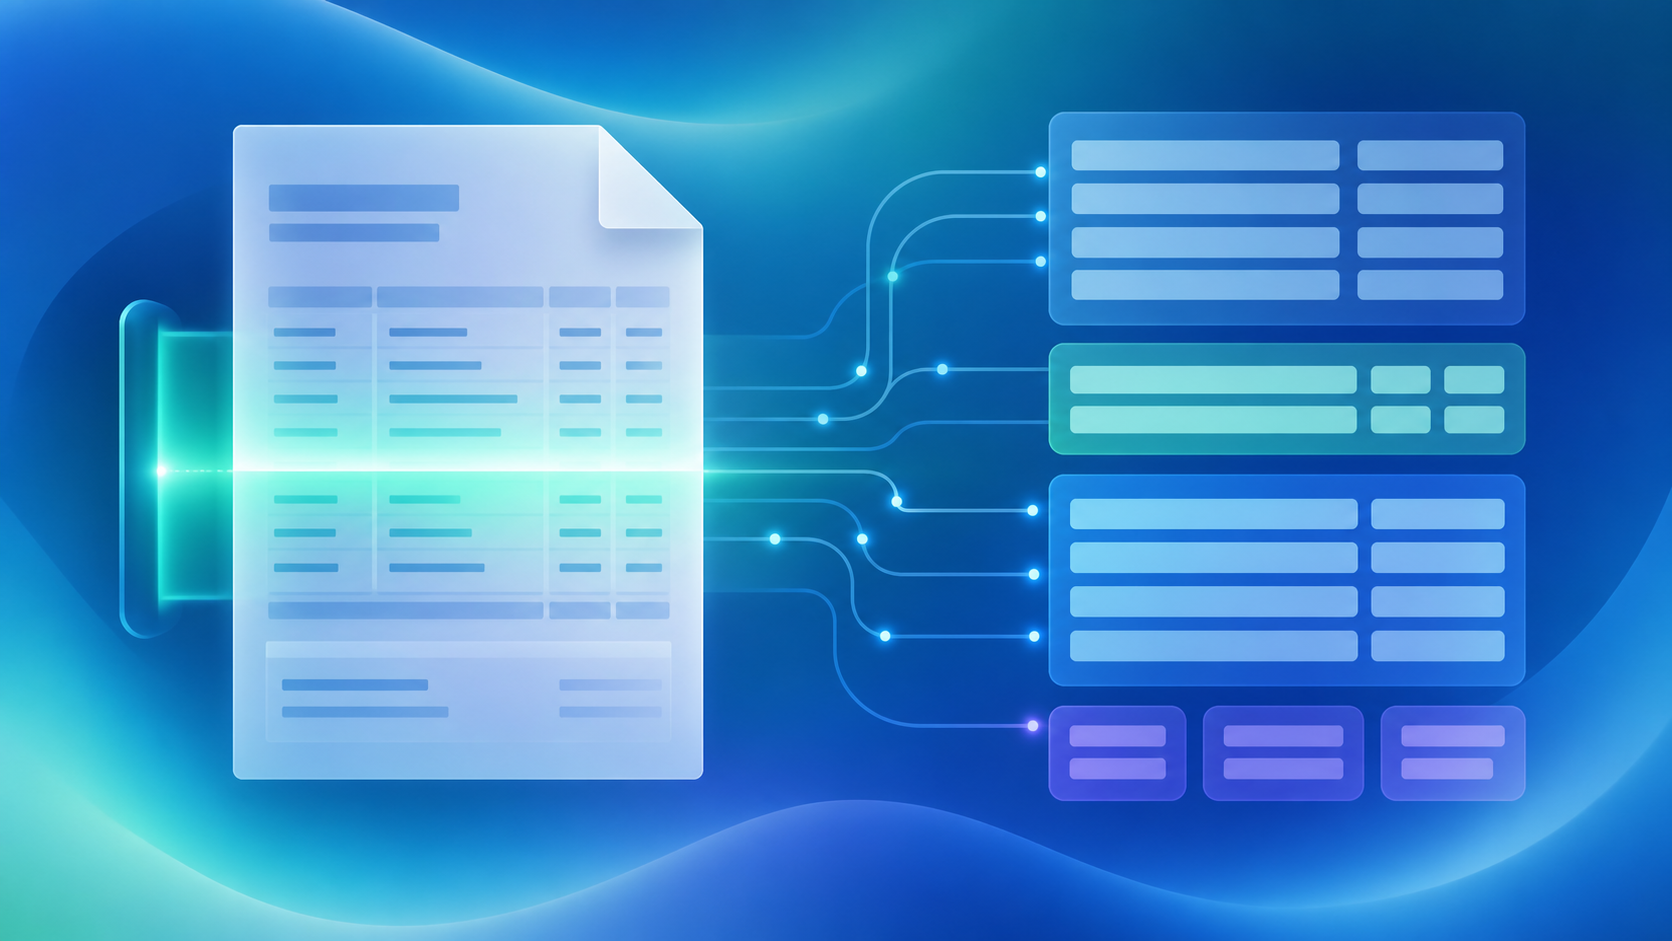
Two layers do the reading. OCR converts document text to characters; image analysis handles a phone photo that arrives rotated, skewed, or shot in low light, correcting orientation before extraction runs, part of a broader workflow for AI-powered paystub and bank statement processing. Classification then routes each captured value to its destination field instead of trusting a fixed position, so a stub listing deductions in a different order still maps correctly.
Accuracy tracks document quality. AI extraction tools report 99% accuracy for AI-powered OCR on clean documents, against below 85% for legacy OCR. Paystub variability pulls that number down, which is why review stays in the loop.
Converting Pay Frequency Into Accurate Monthly Income
Extraction gets you clean line items. Turning them into a means-test number takes calendar math. Weekly pay multiplies by 52 and divides by 12; bi-weekly runs 26 over 12; semi-monthly is a flat 24 periods a year; monthly maps straight across. Each frequency needs its own multiplier before averaging into the six-month CMI window.
Pay Frequency | Periods Per Year | Monthly Income Conversion |
|---|---|---|
Weekly | 52 | Multiply by 52, divide by 12 |
Bi-weekly | 26 | Multiply by 26, divide by 12 |
Semi-monthly | 24 | Flat 24 periods a year |
Monthly | 12 | Maps straight across |
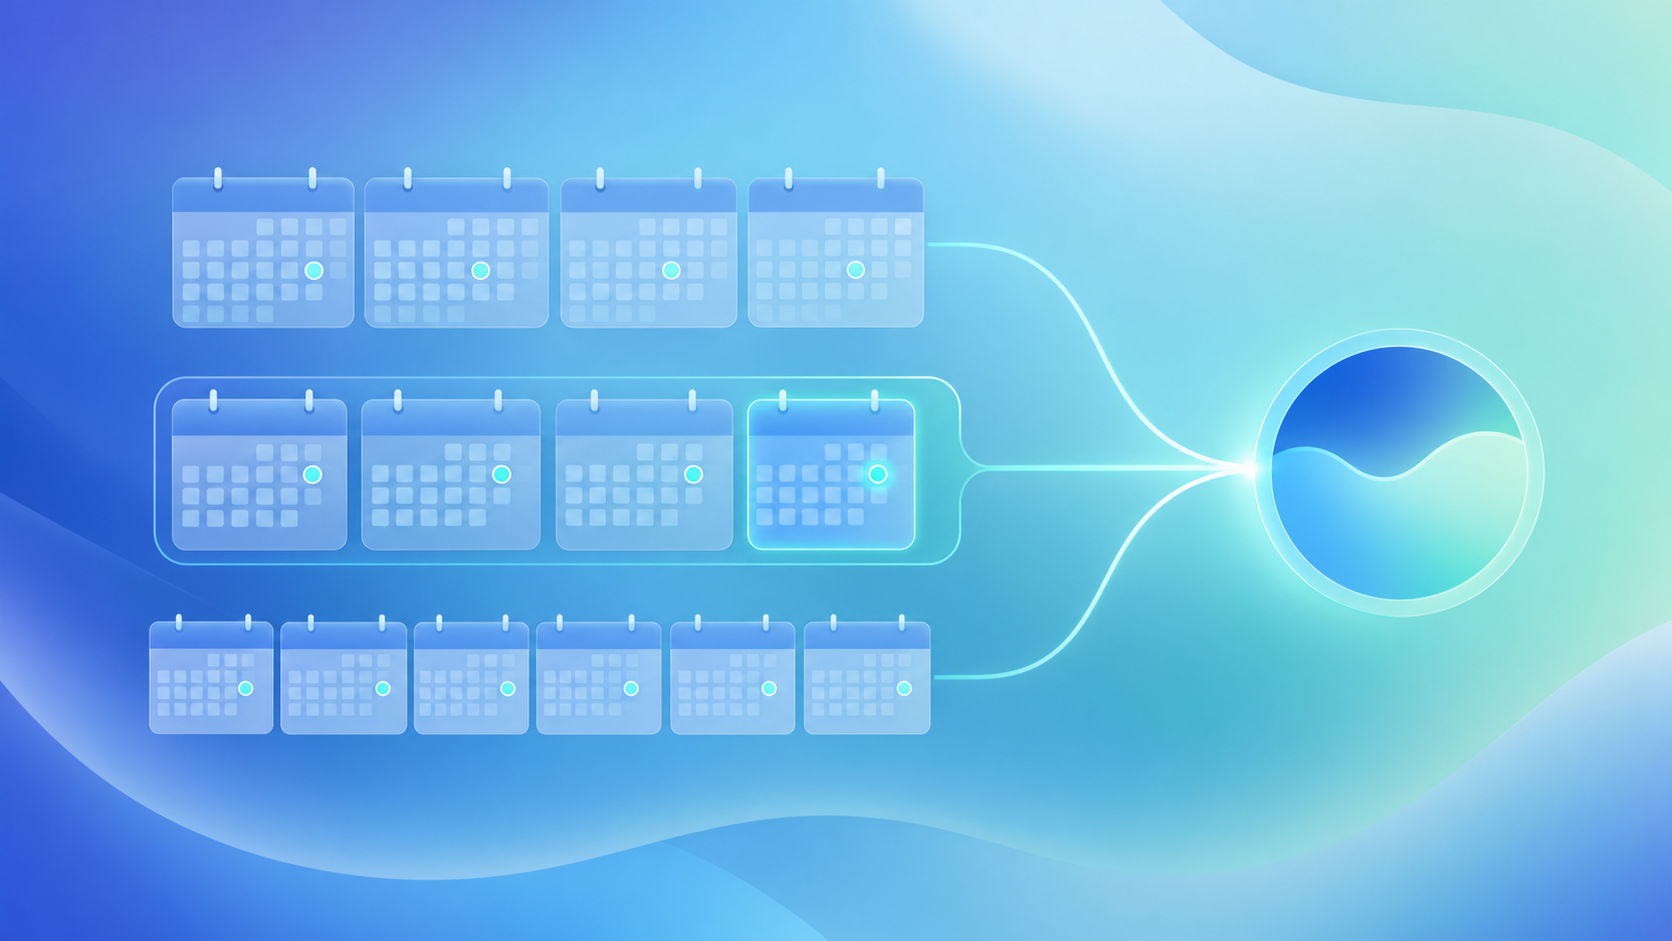
The trap sits in bi-weekly schedules. Six months usually holds 12 checks, but roughly twice a year the calendar drops a 13th inside the window, a nuance that firms automating document collection with AI need to account for. Sum-and-divide averaging catches that extra check and reports real six-month income. Multiply one check by a fixed factor instead and you over-weight income, inflating CMI and possibly pushing an eligible debtor above median.
Two methods handle it. Total every stub and divide across the actual window, or, when only one recent stub exists, take the YTD figure and divide by months elapsed. The first fits stable histories; the second fits new or intermittent employment where waiting stalls the case.
Where AI Parsing Breaks Down: Handwritten Stubs, Gig Income, and Edge Cases
Clean W-2 stubs parse well. The client base for consumer bankruptcy does not always hand you clean ones.
Handwritten paystubs are the clearest gap. Legibility varies too much for reliable extraction, so a hand-written stub still needs manual keying against the original. Self-run clients and gig workers, an Uber driver or a contractor paid per job, have no traditional stub at all. Their income comes from bank deposits, profit-and-loss records, or year-to-date summaries that flow through Schedule I Part 8a instead of a paystub parser.
Cash-economy earnings and non-standard employer formats add friction. When a small employer prints an unusual layout or a client is paid partly off the books, extraction confidence drops and the numbers need corroborating documents. These are scenarios where a custom-built AI solution for bankruptcy can be configured to handle edge cases more robustly.
In each case the parser hands back a draft, not a verdict. The paralegal supplies missing figures, the attorney confirms the income basis, and the AI stays what it should be: the tool that clears transcription work when documents cooperate, not a substitute for judgment when they don't.
Keeping Attorney Review in the Loop
Extracted income feeds court-filed math, so every figure gets verified before it hits PACER. That verification splits along architecture. AI does the messy front-end work: reading paystubs, correcting orientation, pulling line items from formats that vary client to client. Deterministic, rule-based logic handles the statutory back end: the frequency multipliers, the six-month average, the median-income comparison. The means test runs on fixed math, never on inference, so every result traces back to the exact rule that produced it and stays auditable. To learn more about how this is structured, see Glade's specialized service agents for bankruptcy.
The paralegal reviews the extracted figures against the source stubs; the attorney confirms the income basis before signing. Automation clears the keying. Judgment stays with the people whose name goes on the filing.
What to Look for When Reviewing AI Paystub Tools for Bankruptcy
Generic payslip parsers built for lending or HR are a reasonable fit for the use cases they were designed for, such as mortgage underwriting, employment verification, and HR onboarding, and they extract fields cleanly for those workflows. Bankruptcy petition prep needs the calculation logic underneath that extraction, which these tools were not built to provide (based on publicly available information as of July 2025). When you compare tools for bankruptcy work, check for these:
- Field mapping that lands income and deductions directly into Form 122A-1, Form 122C-1, and Schedule I, going beyond a raw data dump. See this case study for how a high-volume bankruptcy firm built its workflow around that capability.
- Frequency-conversion accuracy, including the bi-weekly 13th-check case that trips fixed multipliers.
- Multiple-employer and irregular-pay handling, so a debtor with two jobs or seasonal income still averages correctly.
- YTD calculation support for single-paystub cases where six months of stubs don't exist yet.
- Source traceability tying every figure back to the stub it came from, for audit defense.
- Conflict flagging when a questionnaire figure and an extracted figure disagree, instead of silently picking one.
How Glade AI Automates Income Calculations for Petition Prep
Glade AI is a bankruptcy-first operating system, and uploaded paystubs become Schedule I income automatically. Our AI agents pull line items, then real calendar math and frequency multipliers convert figures to monthly income matching IRS means-test requirements. See how end-to-end bankruptcy filings with Glade AI agents work in practice. The Income Organizer gives you four modes:
- All Paystubs for six-month averaging
- Single-Paystub YTD for non-traditional employment
- Kevin's Method for alternative pay-period averaging
- Period Method for bi-weekly schedules where a 13th check lands in the window
The math stays deterministic. Our means-test engine runs fixed statutory rules, not inference, so every court-filed number is auditable. A confirmed value propagates across 21+ linked petition fields, ending the re-keying. In a live demo, one agent processed 33 pay stubs in under a minute, and firms collapse an 8+ hour petition assembly into under 2 hours.
Handwritten stubs remain a known extraction limitation. To see how Glade automates income calculations across Chapter 7 and Chapter 13 workflows, visit our Glade AI bankruptcy page.
Final Thoughts on How AI Handles Paystub Income in Bankruptcy Prep
The means test runs on income you can prove, and one mistyped stub moves every number under it. Letting AI pull the line items while fixed statutory math runs the average means your team spends time on review instead of retyping. Handwritten and gig-income cases still need your eyes, and that's the point: the tool clears the work, you keep the call. To see how Glade turns paystubs into means-test-ready income, book a demo.
FAQs
Can AI paystub parsing handle self-run or gig-worker income for a bankruptcy petition?
No, not through a paystub parser. Self-run clients, gig workers, and contractors have no traditional stub, so their income comes from bank deposits, profit-and-loss records, or year-to-date summaries that flow through Schedule I Part 8a instead. Glade's paystub extraction works on client-uploaded W-2 stubs; irregular income still needs corroborating documents and manual entry.
What's the difference between AI paystub parsing in Glade AI versus a generic payslip parser built for lending or HR?
Generic payslip parsers extract fields cleanly but stop at extraction. Bankruptcy work needs the calculation logic underneath, so look for a tool that maps income and deductions directly into Form 122A-1, Form 122C-1, and Schedule I, handles the bi-weekly 13th-check case, supports YTD math for single-paystub cases, and ties every figure back to its source stub. Glade's Income Organizer runs those conversions with a deterministic means-test engine instead of a raw data dump.
How does Glade AI keep means-test calculations accurate when the paystub extraction is AI-driven?
Glade splits the work by architecture: AI reads the messy front end (paystubs, orientation correction, line-item extraction), while deterministic rule-based logic owns the statutory back end (frequency multipliers, six-month averaging, median-income comparison). The means test runs on fixed math, never inference, so every result traces back to the exact rule that produced it and stays auditable. A paralegal reviews the extracted figures against the source stubs and the attorney confirms the income basis before signing.
Why does converting bi-weekly pay to monthly income trip up so many bankruptcy tools?
A 13th bi-weekly check can land in the CMI window; fixed multipliers over-weight it. Glade's Period Method uses sum-and-divide averaging to catch it.
Can Glade AI parse handwritten paystubs?
No. Handwritten paystubs are a confirmed extraction limitation because legibility varies too much for reliable reading, so those stubs still need manual keying against the original. Firms with cash-economy or informal-employer clients should plan for manual entry on those documents while the parser handles clean W-2 stubs.