AI Reads Credit Reports into Schedules D, E, F Sep 2026
Every creditor on your schedules has to land on the bankruptcy creditor matrix with a complete, correctly formatted mailing location, or that party never hears about the case. Do it by hand across three bureaus and version drift creeps in fast: one contact line gets fixed in one place but not the others. Here's how reading the report semantically instead of by column position closes that gap before anything files.
TLDR:
- Miss a creditor on the matrix and that party gets no notice, so the debt can survive discharge
- Schedule D holds secured debts, E/F Part 1 priority claims, E/F Part 2 general unsecured; wrong routing breaks payment order
- Follow strict matrix formatting: single column, 40 characters per line, account numbers off the first line
- AI reads each tradeline's function across Experian, TransUnion, and Equifax and routes it to the right schedule without per-bureau setup
- Glade auto-populates Schedules D, E, and F from tri-merge reports before paralegal review, collapsing an 8-plus hour petition into roughly a 2-hour workflow
What the Bankruptcy Creditor Matrix Is and Why It Anchors Every Filing
The creditor matrix is the master list of every creditor's name and mailing location, filed with the petition, that feeds the court's noticing system and becomes the mailing list for nearly every notice the case will send. Get a contact line wrong or leave a creditor off, and that party never gets notice.
Everything entitled to notice belongs on it:
- Every creditor on the schedules, secured and unsecured, with a complete mailing location
- Taxing authorities and government agencies with a possible claim
- Codebtors, and parties to leases and executory contracts
- Anyone else entitled to notice, such as attorneys who have appeared
The court uses this file for noticing and claims information, which is why its accuracy anchors the entire filing.
How Schedules D, E, and F Differ and What Belongs on Each
Three schedules feed the matrix, and each turns on how a debt is classified.
- Schedule D: creditors holding claims secured by property. A secured debt is backed by collateral the lender can take if payments stop, like a mortgage or car loan.
- Schedule E/F, Part 1: priority unsecured claims. No collateral, but the Code moves them ahead in payment, such as certain taxes, domestic support obligations, and wages owed.
- Schedule E/F, Part 2: general nonpriority unsecured claims, the everyday debts like credit cards, medical bills, and personal loans.
Schedule | Claim type | Collateral | Examples | Treatment |
|---|---|---|---|---|
Schedule D | Secured | Yes, the lender can take the collateral if payments stop | Mortgage, car loan | Paid per the collateral; keep the asset by staying current |
Schedule E/F, Part 1 | Priority unsecured | No | Certain taxes, domestic support obligations, wages owed | Paid first; usually outlast the case |
Schedule E/F, Part 2 | General nonpriority unsecured | No | Credit cards, medical bills, personal loans | Erased or paid at a fraction |
Classification determines payment order and what survives discharge. Priority debts get paid first and usually outlast the case; nonpriority debts are the ones bankruptcy erases or pays at a fraction. Route a creditor to the wrong schedule, and both treatments break.
How to Prepare a Bankruptcy Creditor Matrix: Format Rules Courts Enforce
The matrix gets machine-read into the court's noticing system, so formatting is enforced, not suggested. The rules that recur across district instructions look like this:
- One single column, aligned to the left, with a one-inch margin
- No more than five lines per creditor, at least one blank line between each
- No more than 40 characters per line, including spaces
- Two-letter state abbreviations in caps; nine-digit ZIPs hyphenated
- City, state, and ZIP on the last line
- No headers, footers, or page numbers; no special characters
- Account numbers off the first line
Each district publishes its own variations on fonts, margins, and creditors-per-page. Check yours before you file.
The Bankruptcy Creditor Matrix Verification Requirement and the Official Forms
The verification of creditor matrix is a signed declaration confirming the list of creditors is true and correct. The debtor or counsel signs it, and most districts require it filed alongside the matrix itself.
It sits among the official forms the petition already carries, each doing a distinct job:
- Form 106Dec: the declaration under penalty of perjury that the schedules are accurate
- Form 106Sum: the summary of assets and liabilities
- Form 106J: the debtor's monthly expenses
- Form 107: the Statement of Financial Affairs
- Form 121: the statement about the debtor's Social Security number
- Form 103B: the application to waive the filing fee
The matrix draws on the same creditor data these schedules hold, but it is a separate, machine-readable list. The schedules classify and describe debts; the matrix is the flat mailing-location file the noticing system reads.
What Happens When You Leave a Creditor Off the Bankruptcy Creditor Matrix
Miss a creditor on the matrix and that party never gets notice, so the automatic stay may not stop its collection efforts and the debt can survive discharge. An inaccurate list is a live risk, not a clerical footnote.
How it plays out depends on the chapter:
- In no-asset Chapter 7 cases where creditors get nothing anyway, courts often treat an omitted debt as discharged regardless, though this varies by circuit.
- In Chapter 13, an omitted creditor left out of the plan can pursue the debt because it never had the chance to file a claim.
Find a creditor after filing and you amend the schedules and the matrix, then serve the added creditor with notice of the case and any deadlines.
Why Manual Creditor Entry Fails at Volume
It's 6 p.m., the petition's due tomorrow, and the credit report is still three bureau PDFs nobody has keyed in. Building the schedules and matrix by hand means transcribing every tradeline from Experian, TransUnion, and Equifax, then squaring up the duplicate and misformatted mailing locations those bureaus disagree on.
The same creditor gets typed again into the matrix, then onto Schedule D, E, or F. Each pass adds a way to fail:
- Transposed digits in a mailing location that sends notice nowhere
- A creditor dropped entirely between the report and the schedule
- Account numbers landing on the first line, tripping the court's scanner
- Version drift when one creditor's contact line gets fixed in one place but not the others
At 50 or more cases a month, one paralegal carries all of it, a friction point that compounds fast at volume.
How AI Reads Credit Reports and Routes Creditors to the Right Schedule
Feed a tri-merge report into an AI that reads the function of each tradeline instead of its label or column position, and every account routes to Schedule D, E, or F without per-bureau setup. A revolving credit card lands in F, a secured auto loan in D, a tax lien in the priority side of E/F, no matter how Experian, TransUnion, or Equifax order or name the fields.
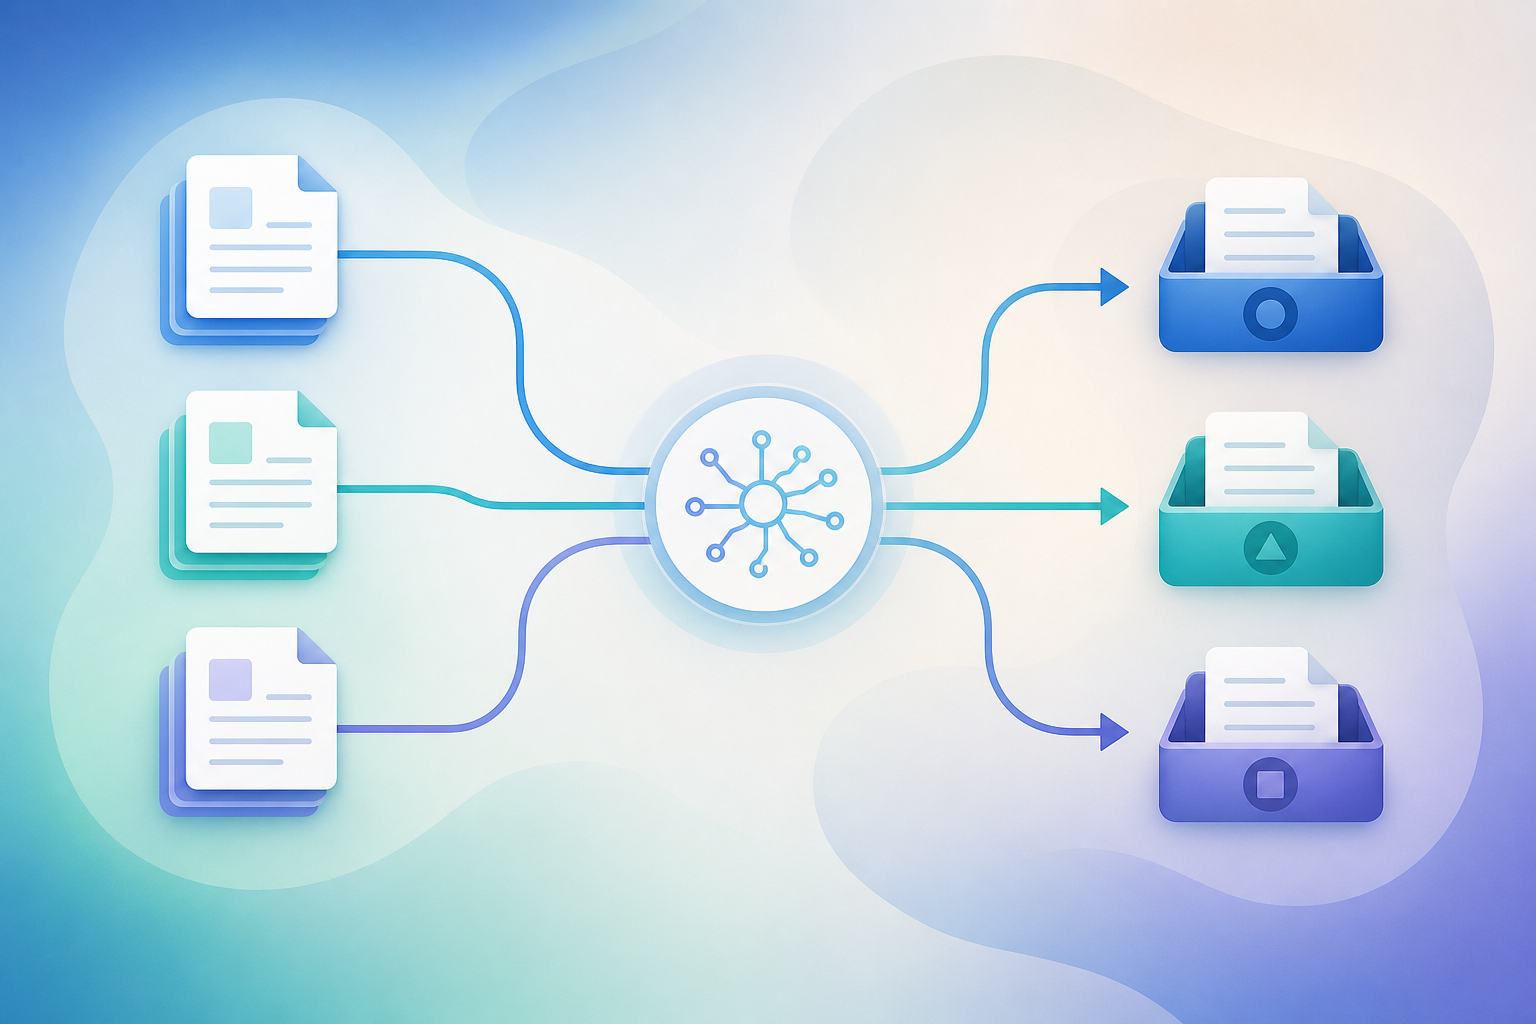
Older keyword or position-based parsers break the moment a bureau reorders a section or relabels an account type. Semantic extraction reads the meaning, so format variation stops mattering. This is what Glade's AI Schedules Builder handles at the parsing layer.
The boundary stays clear, though. Credit reports do not capture county-level judgment liens or local court filings, so those still require an independent title or county records search before the schedules close.
Keeping the Human in the Loop: Review, Overrides, and Accuracy Checks
Auto-population raises the obvious question for a court filing: can you trust the output? The workflow that answers it keeps the attorney in the decision seat. AI drafts the schedules and matrix from extracted tradelines; a paralegal and attorney review before anything files.
Where two sources disagree on a creditor's mailing location or balance, the conflict surfaces with full provenance, so the reviewer sees which document supplied which value and resolves it. Every auto-filled field carries source attribution back to the report or statement it came from.
The judgment calls stay manual: exemption elections, disputed-debt flags, and contingent or unliquidated designations are attorney decisions, not extraction outputs. Glade's AI agents for bankruptcy are designed around exactly this division of labor.
From Schedules to a Court-Ready Matrix and Certificate of Service
Once the schedules hold a complete, deduplicated creditor list, that same data flattens into the machine-readable matrix the court's noticing system ingests. The list drafts once; the matrix falls out of it.
From there the matrix stops being a filing and starts working as a mailing list. Motions, Chapter 13 plans, and notices for creditors added by amended schedules all get served on the full matrix under Federal Rule of Bankruptcy Procedure 2002. Each service is followed by a certificate of service stating exactly who was served, how, and when.
Every creditor you add later re-enters the matrix and joins that service loop.
How Glade AI Auto-Populates Schedules D, E, and F Without Manual Entry
Glade's document intelligence ingests tri-merge credit reports and routes each tradeline to Schedule D, E, or F across all three bureau formats without per-bureau setup. One click auto-populates Schedule D and the creditor matrices, pulls prior bankruptcies and civil judgments, and deduplicates mortgage statements so consecutive months update one creditor entry instead of stacking duplicates. See how a high-volume bankruptcy firm reworked its workflow with exactly this capability.
The attorney stays in the seat. AI pre-populates fields before paralegal review, every value carries source attribution back to its document, and re-running an agent preserves attorney-confirmed decisions. County-level judgment liens sit outside the credit report, so verify those separately.
That collapses an 8-plus hour petition assembly into roughly a 2-hour workflow. The full pipeline is detailed in end-to-end bankruptcy filings with Glade AI agents. See the full pipeline on Glade's bankruptcy page.
Final Thoughts on Managing the Bankruptcy Creditor Matrix at Volume
Manual entry breaks down fast when 60 cases a month all flow through one paralegal keying tradelines by hand. Pull your creditor data once, route it to the right schedule, and let the machine-readable matrix fall out of that same clean list so notice reaches everyone entitled to it. Grab a demo and see the full creditor matrix and schedule workflow in action.
FAQs
Can AI build a bankruptcy creditor matrix without manual entry?
Yes. AI reads the function of each tradeline on a tri-merge credit report and routes it to Schedule D, E, or F, then flattens that deduplicated creditor list into the machine-readable matrix the court's noticing system ingests, so the list drafts once instead of getting keyed in three times. A paralegal and attorney still review before anything files, and county-level judgment liens sit outside the credit report, so those need a separate title or county records search.
What's the difference between the creditor matrix and Schedules D, E, and F?
Schedules D, E, and F classify and describe debts (secured, priority unsecured, and general nonpriority) while the creditor matrix is a separate flat mailing-location file the court machine-reads to build its mailing list. Both draw on the same creditor data, but the matrix carries only names and mailing locations in a strict format, no classification.
How does Glade AI keep accuracy high when auto-populating petition schedules?
Glade keeps the attorney in the decision seat: AI pre-populates fields before paralegal review, every value carries source attribution back to the report or statement it came from, and re-running an agent preserves attorney-confirmed decisions instead of overwriting them. Where two sources disagree on a creditor's mailing location or balance, the conflict surfaces with full provenance so the reviewer resolves it, and judgment calls like exemption elections and disputed-debt flags stay manual.
What happens if you leave a creditor off the bankruptcy creditor matrix?
The debt can survive discharge. See the full breakdown by chapter in the body section above.
What are the format rules for a creditor matrix?
See the formatting rules section above for the full list. The key rules: 40 characters max per line, five lines per creditor, no headers or special characters, and two-letter state abbreviations with hyphenated nine-digit ZIPs. Each district publishes its own variations, so check yours before filing.